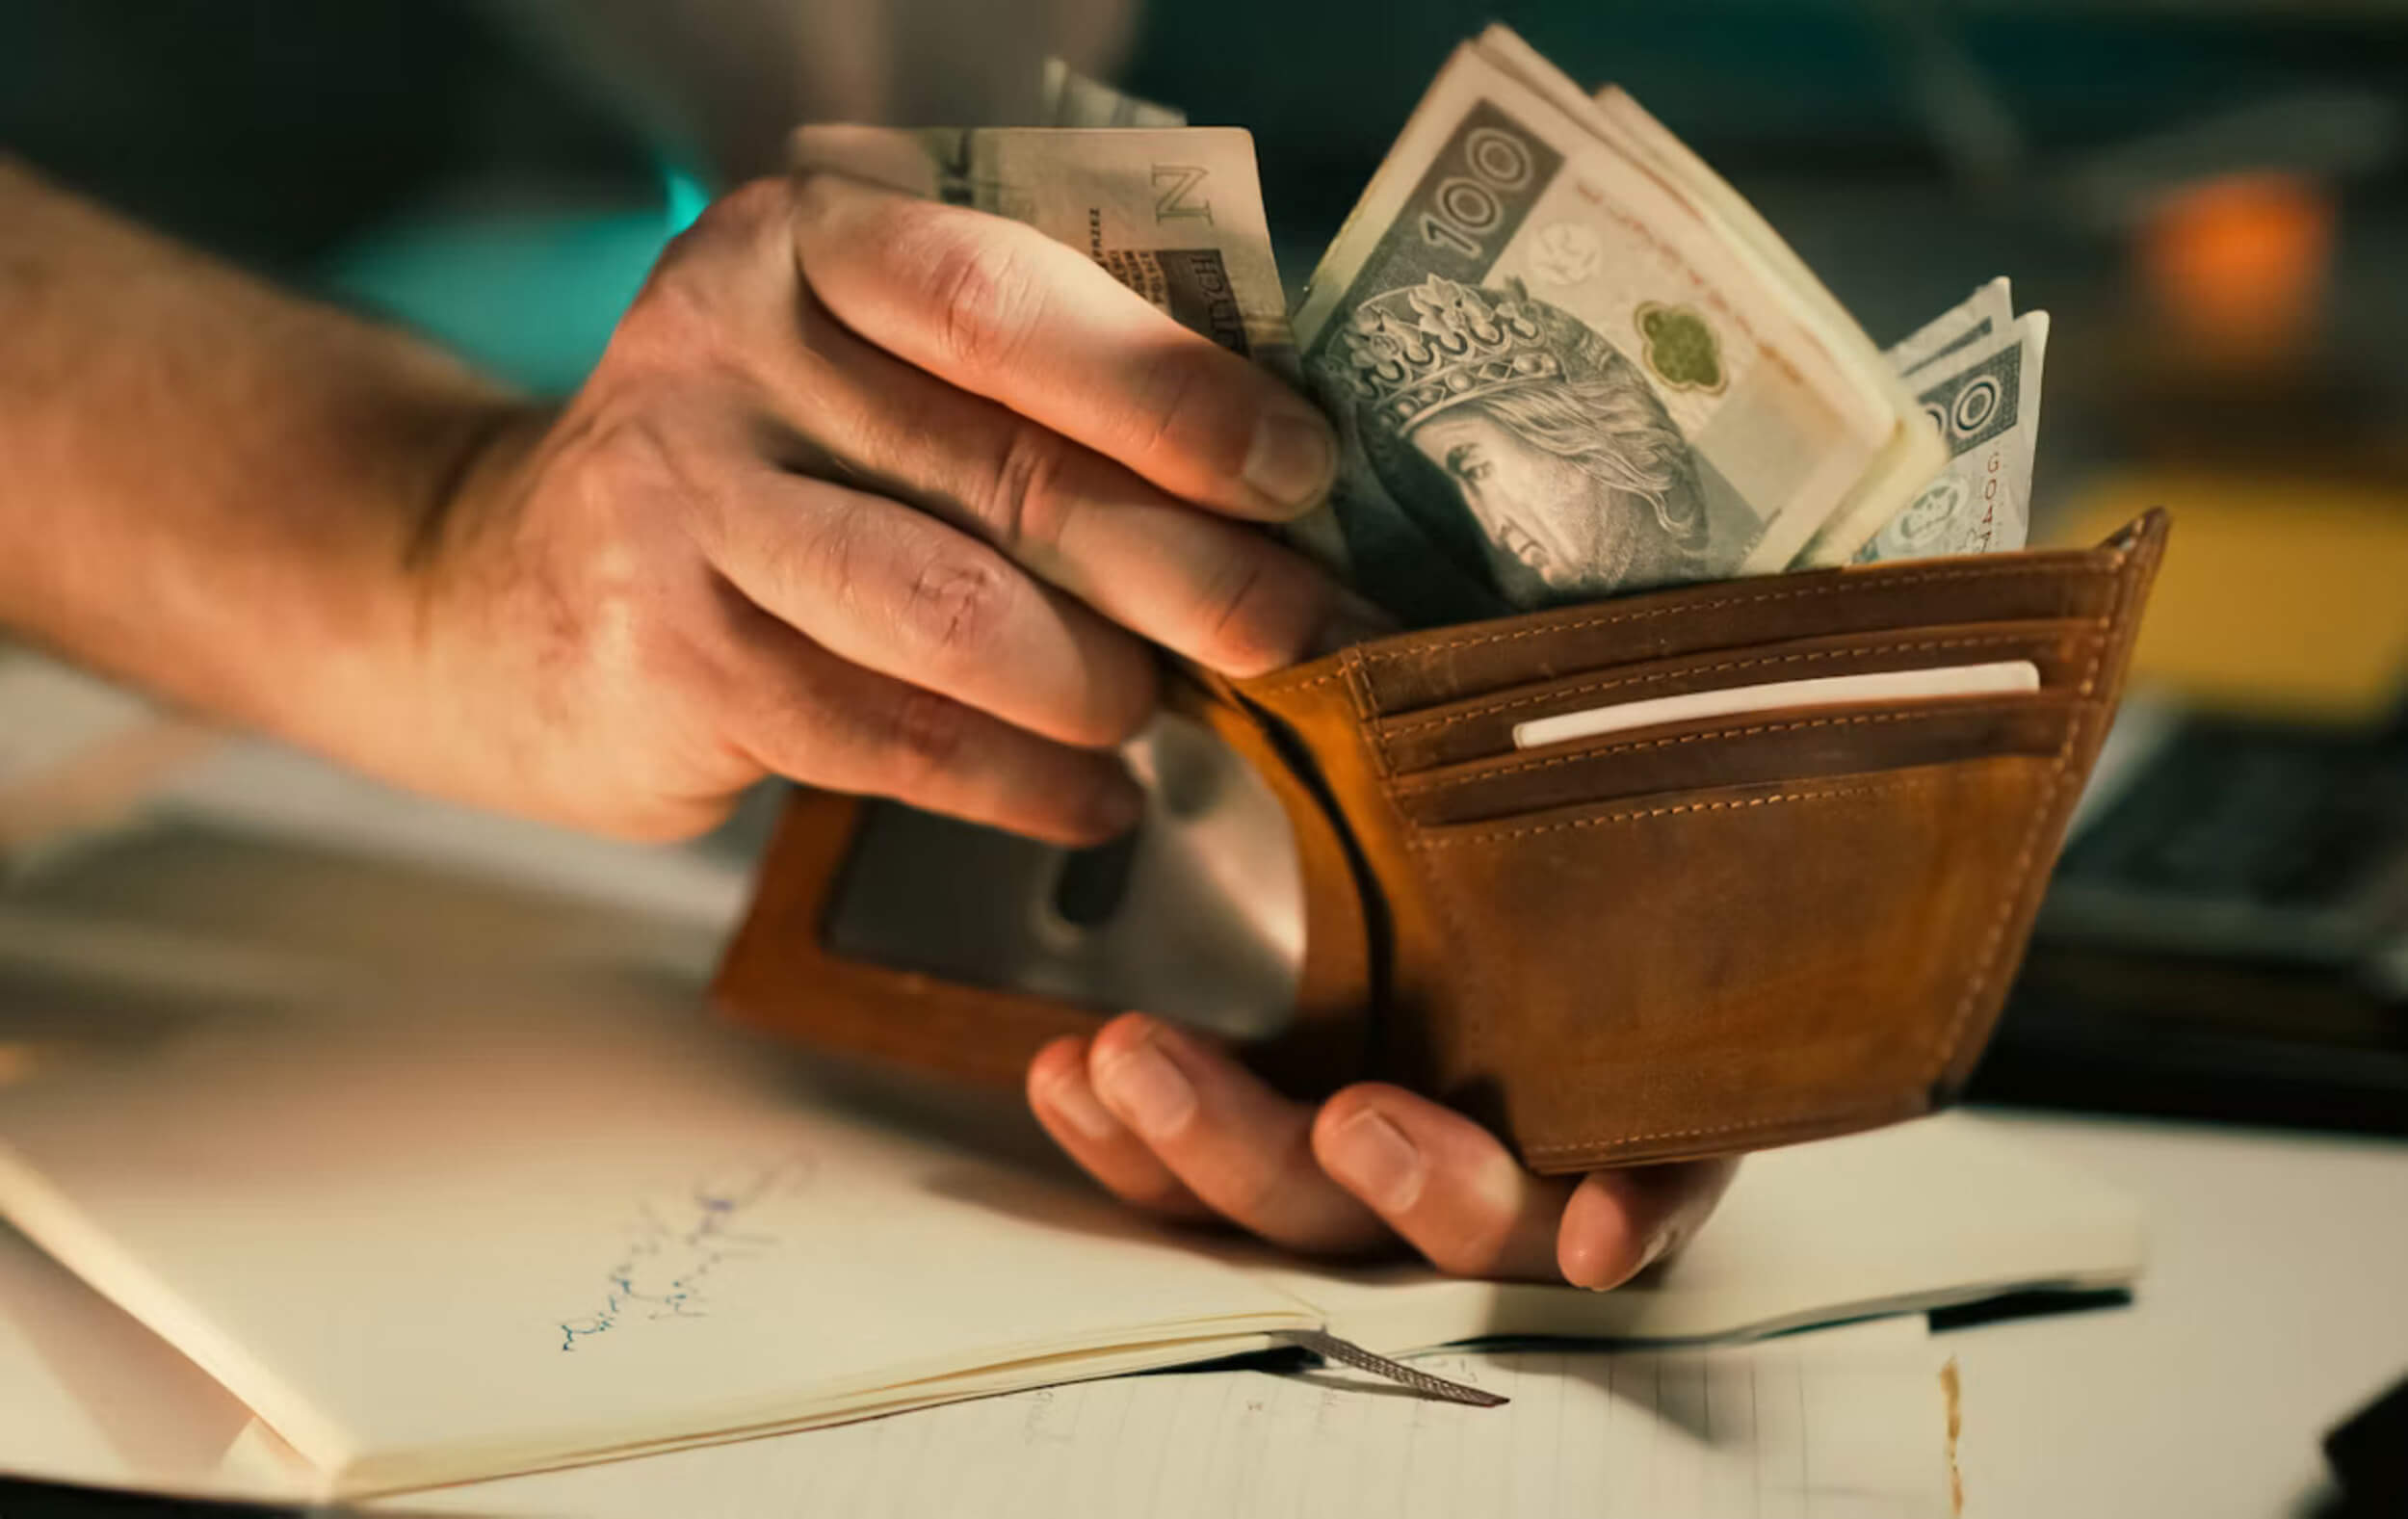
The number in your bank account never tells the whole story.
You check your balance and feel a little relieved. Then you remember the electricity bill is due, groceries still need buying, and payday is several days away. Suddenly, that number does not feel quite so reassuring.
When money feels hard to keep up with, it is easy to think you need to earn more before you can do anything about it. More income can help, but you do not need a high income or a perfect budget to start feeling more in control of your money. First, you need to know what is coming in, what needs to be paid, and what you have left to work with.
From there, small choices become easier to make. You can plan for a bill before it arrives or decide whether a purchase fits this week. You do not have to fix everything today. Start with the part of your money that feels least clear, and give it your attention.
Get a Clear Picture of Your Money
A bill can feel more stressful when you are unsure what is left to pay. Getting the numbers in one place gives you a starting point and more control of your money.
See What Comes In and What Goes Out
Start with the amount you actually receive after deductions. Then look at what you spent recently. A bank statement can help, but a notebook or simple spreadsheet works too.
For now, sort your spending into two groups:
- Costs you need to cover, such as housing, food, transport, and bills
- Costs you can change, such as meals out, subscriptions, and treats
You might spot a payment you had forgotten or find that groceries cost more than you thought. That is useful information, not a reason to feel bad. You only need a clear picture of a typical month. There is no need to record every purchase forever.
Put Your Bills and Paydays on One Calendar
Write each bill’s amount and due date on a calendar. Add your paydays too. You can use paper, your phone, or whatever you already check.
A month can look fine when you add up your income and bills, yet one week may still be tight. For example, rent, electricity, and a loan payment might all be due before your next payday. Seeing that week ahead of time gives you a chance to plan for it.
If several bills land at once, ask the providers whether you can change a due date. It may not always be possible, but a different date could make payments easier to manage.
Make a Plan for the Money That Remains
Once you have allowed for essential bills, decide what the remaining money needs to do. Part may go toward everyday needs, part toward things you enjoy, and part toward a goal if you can afford it.
Keep the plan honest. If you usually buy lunch at work or enjoy a weekend coffee, include it. Leaving out normal spending can make a plan hard to follow.
You do not need to decide where every last coin will go. Knowing roughly what is available for the week can help you choose with more confidence than hoping there is “probably enough” in your account.
Make Upcoming Costs Less Surprising
The next bill is not always a monthly one. Looking a little further ahead can give you more control of your money when a cost that is easy to forget comes around.
Set Aside Money for Predictable Extra Costs
School supplies, annual fees, holidays, and routine vehicle work may not show up every month. Still, you often know they are coming. Without a plan, even an expected cost can feel sudden.
Pick one expense due in the coming months. Work out roughly how much it may cost, then see whether you can put a small amount aside each payday. If the amount is too much, save what you can and plan how you will cover the rest.
Keep this money separate in your mind from savings for unexpected problems. Its job is to pay for something you already know is coming.
Build a Small Buffer for the Unexpected
A broken appliance or an urgent trip can arrive without warning. Having some money set aside may give you a choice besides borrowing or putting another bill off.
Start with an amount that fits your situation. For one person, that might be a little each payday. For someone else, saving may need to wait until their most urgent bills are covered. There is no single starting amount that works for everyone.
If you have to use the money, it has done its job. You can build it up again when you are able. That is what a buffer is for: helping you through a difficult moment.
Take the Pressure Out of Everyday Decisions
Once your bills and basic needs are covered, smaller choices can still feel stressful. A few simple habits can help you decide what fits without questioning every purchase.
Pick one area where you often spend more than you meant to, such as takeaway meals or online shopping. Set an amount that feels comfortable for the week or month. This is a choice you make for yourself, not a rule you have failed if plans change. If a higher electricity bill comes in, for example, you might spend a little less on takeaways that week. When costs settle, you can adjust again.
Next, look at payments that happen without you making a new choice. You may still be paying for a streaming service you rarely watch or a membership you stopped using. Check your bank statement for these charges and ask which ones you want to keep. A service you enjoy and use may be worth the cost. Cancelling one you have forgotten about frees up money for something you care about more.
Larger purchases deserve a little more thought, especially if they would leave the rest of the month tight. Before buying, check the full price, including delivery or any extra fees. Then look at what still needs to be paid before your next payday. You can give yourself a day to think if the purchase is not urgent.
Pausing does not mean you have to say no. Sometimes you will see that it fits and buy it without worrying. Other times, waiting until next payday will feel better. Either way, you have made a choice based on what is happening with your money, rather than on a guess. That is one way to feel more control of your money in everyday life.
Deal With What Is Weighing on You
Small changes to spending can help, but they may not ease a worry about debt or a bill you share with someone else. Give that concern its own plan.
If debt is on your mind, write down each balance, minimum payment, due date, and interest rate. Seeing the details together can help you work out what must be paid and whether you can afford anything extra. If you can, choose where that extra amount will go. If you think you may miss a payment, contact the lender early and ask what options are available. A reputable financial counsellor may also be able to help you review your choices. www.consumerfinance.gov
Money can feel harder to manage when another person depends on the same funds. If you share costs with a partner or someone in your household, start with one issue. You might say, “The electricity bill is due on Friday. How much can each of us put toward it?” Agree on the amount, the date, and who will make the payment.
You do not have to settle every money disagreement in one conversation. Handling one real concern gives you a clearer next step and more control of your money where it matters right now.
Conclusion
Think back to checking your balance before payday. The number in your account may be the same, but it means more when you know which bills are due and how much is available for the days ahead. You can make a decision without trying to keep every amount and date in your head.
Feeling more control of your money does not mean life will stop bringing surprises. It means you have a way to check where you stand and choose what to do next. If a cost changes, you can look at your plan again and adjust it.
Choose the step that would help you most this week. Write your bill dates on a calendar, check a recurring charge, or talk through one shared payment. Keep it small enough that you can actually do it. Once that step has helped, you can decide what needs your attention next.
A clearer picture may not solve everything at once. It can, though, make the next money decision feel less like a guess.